The horizon is not so far as we can see, but as far as we can imagine

Category: Economics Page 6 of 100

How Dependent Is Canada On The US?

This “issue” has flaired up again as Trump attacks Canada again.

The short answer is that in the short term Canada is moderately dependent on the US and the long term it is hardly dependent on America at all.

Right now we (Canada) have a lot of trade with the US. We buy mostly finished goods, and pay fees to American tech and copyright holders. The US buys oil (which it cannot easily substitute away from in the short term). The US buys cars from us (#2, but deceptive, since they’re made by US companies in Canada), a small amount of machinery like nuclear power equipment, and a grab bag of other industrial goods. We also sell Potash (about 80% of what the US needs) and aluminum to the US, for which there is no easy substitute: these things are in global shortage, and the best alternative for potash is Russia and despite various bullshit about American/Russian alliances, Russia doesn’t trust the US at all and would not be a reliable trade partner. Without potash American farmers are screwed, since it’s used for fertilizer. America can’t significantly improve domestic potash production, there isn’t enough in America.

There’s substantially nothing we buy from the US that we can’t get from China for less or Europe for a bit more. And what the US sells Canada is high value add goods, not resources. We’re a valuable customer.

And, at the brass tacks level, if all trade stopped tomorrow, Canada could feed itself and would have plenty of energy. Our houses would stay hot in the winter and cool in the summer, our trucks would have gasoline and diesel, our trains would run and our planes would fly.

Canadian dependence on America is about 80 to 90% a legacy issue. We currently do a lot of trade with America, but we don’t have to. We can sell manufactured goods to Europe, and resources to China and buy from China and Europe and various other nations. Nothing we get from the US is a “must have with no feasible replacement.”

So the game is very much along the lines of the old joke about saying nice things to a barking dog while you find a rock. Not that we will ever fight the US unless they invade, but we just need time to disentangle our economies and move to reliable trade partners.

America could hurt us a lot if they cut of trade, but it wouldn’t be a mortal blow and we would recover. We’d prefer to do it slow, but if we have to do it on an emergency basis it can be done.

Canada doesn’t need the US. It just needs some time to change trade partners, and that’s what Carney is doing, because as he has said, it no longer makes sense to do business with the US.

We’ll talk a bit more about trade with the US from a global perspective soon, but basically the US has a legacy trade position: no one needs to buy from it any more unless they’re stupid (Europe refusing to buy Russian gas). Selling to it is still necessary for many nations, but that will become less true over time.

America’s prosperity and power are both legacies, they have no solid foundation to stand on any more. Ironically Canada is in a better position in the middle to long term than America simply because it only has 40 million people and is a continent sized country with a continent’s worth or resources. The only significant danger is an American invasion.

This site is only viable due to reader donations. If you value it and can, please subscribe or donate.

Silver Short Take

Jaysus on a popsicle, Mary and all the Saints do I have some egg on my face. Since January 27 silver has been on one seriously wicked ride. I’ve been banging my head to Metallica’s Whiplash for the last ten days.

So, WTF happened?

In short: from where I sit the paper markets are trying to create a force majeure situaiton for March contracts. The market is incredibly volatile and highly illiquid. Traders are draining the vaults of bullion. Indeed, as Dario notes, “Silver physical deliveries at the Comex just crossed 4,000 contracts (~20m/oz)and we are only 6 days into February.” That’s nucking futs. 

If the Comex defaults to force majeure (SHFE is a bit of a different matter) the Comex will lose all credibility as a fair functioning market dedicated to price true discovery. Never mind that silver prices in the USA has been a cozy Fed-supplied rentiers market for decades, should this happen businesses will begin a mad scramble to source silver for themselves. That leads to supply and demand chaos. Bad. Vewwy bad.

On the SHFE–Shanghai–one day last week over 1.3 billion ounces of silver volume were traded. That’s one year of global demand in a day. The Chinese government’s motto regarding traders shorting silver on the SHFE seems to be FAFO. The Chinese are cracking down hard. Why? Well, to produce one gigawatt of power using solar panels requires 1 million ounces of silver.

You read that right. One million ounces.

Fundamentals matter. Global demand is strong. Businesses need silver for industrial applications beyond just solar panels and dentistry. But traders can keel-haul fundamentals sometimes with epically shitty consquences. Watch this video by Dario starting at minute 6:43 for how this possibly plays out.

It’s ugly. And it seems to me that maintaining a viable silver market is now fully in the hands of the Chinese. US traders are determined to destroy price discovery and reinstate the cozy rentiers market in the US.

I have no idea how this will end.

Are The Boomers To Blame For America’s Decline?

It’s common to slap all the blame on Boomers, but it’s not really fair, though they certainly did plenty of harm. (Yes, some Boomers, elites are more to blame, yadda, yadda.)

But it wasn’t just the boomers. The so-called Reagan Republicans included a ton of GI Generation and Silents. The issue is that the people who created the FDR system weren’t GI Gen, they were Lost and Missionary generation. GI Gen and later lived in the economy created by those generations, but they didn’t really understand how and why it worked because they weren’t adults during the 1920s, so they didn’t get what it was reacting against or what it was trying to fix and avoid a recurrence of.

GI Gen and Silent leaders looked at all the rules FDR and co had put in place and they didn’t really understand why they existed: the rules looked stupid, there seemed to be tons of them,  and they figured “we’re smarter than they were, we won’t do stupid things and life will be a lot easier with less regulation.”

Well that was the rationalization: the other issue was simple enough. Getting rid of the rules let a lot of people become rich and even the middle class thought they’d benefit (and many did, with rising housing and stock prices and lower taxes.) The rules had, quite explicitly, been intended to make sure there couldn’t be another Gilded Age nor another roaring twenties — no stock bubbles, no super rich.

But, of course, a lot of people, especially with power, wanted to become super-rich, or at least richer and getting rid of the rules that were meant to stop that was a no-brainer. Enough middle class people were convinced to go along, and enough racists also joined in (Reagan and Nixon ran heavily on racism.) So a coalition was created which destroyed what had come before.

This started before Reagan, as someone will chime in to tell us, but Reagan was the formalization, the big break.

It happened because people wanted unearned wealth, and because the old system had broken (oil spikes, end of Bretton Woods, end of gold money, staglfation, and no one knew how to fix it (or no one anyone was willing to listen to) because the architects were all old or dead.)

So when offered “you can get rich or at least affluent without work and stick it to the niggers too” a lot of people took that deal. It wasn’t just the Boomers—Silents and GI were key to it, more key than the Boomers in the early years. It’s just that they’re all dead now so we blame the Boomers. Gen-X was complicit, but were still children when the key changes were made.

Boomers get all the blame, but they didn’t start the fire that burned down the old order, they simply threw fuel on it (Clinton, especially) when they could.

This site is only viable due to reader donations. If you value it and can, please subscribe or donate.

How Boeing Made Record Profits And Burned Down The Company

One of the most important things to understand about companies and countries both is the difference between sustainable prosperity and burning down the house.

You’re probably aware that Boeing has serious problems. Those problems have been obviously “on the way” for a long time. When Boeing moved its headquarters from Seattle (where it makes most of its planes) to Chicago, the writing was on the wall.

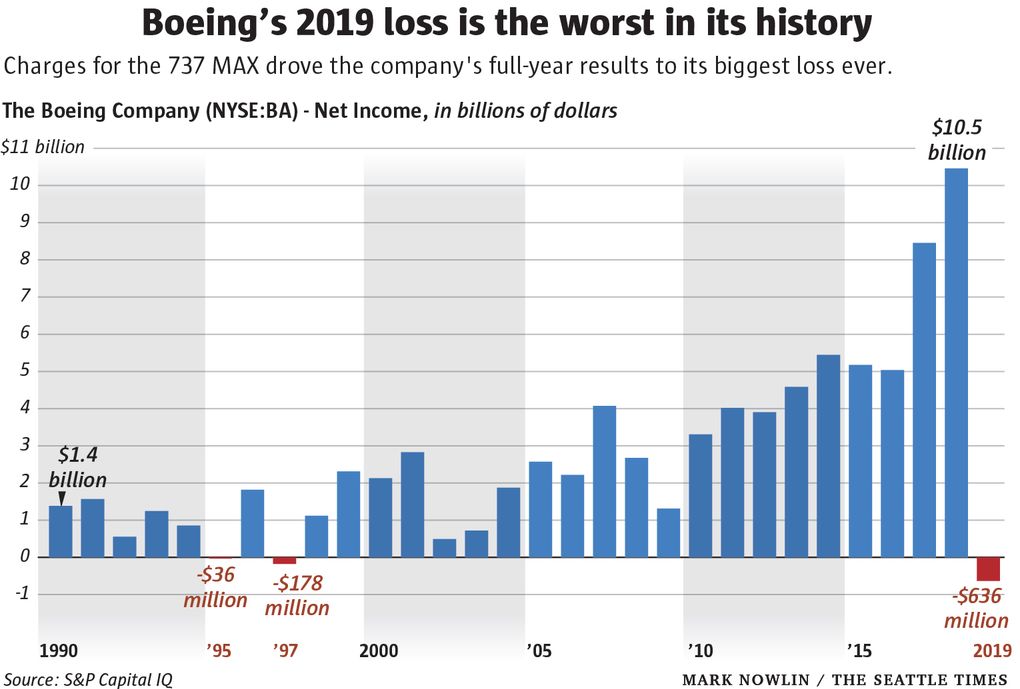
BUT it was also a good time to buy Boeing stock:

The move to Chicago meant that Boeing’s executives had moved away from the manufacturing floor. It was the sign that Boeing’s culture was no longer “Engineering from top to bottom” but finance driven. And that emphasis on finance, on juicing profits, increasing executive salaries and driving up stock prices (those stock options don’t pay otherwise) had an effect. You can see it in the chart above.

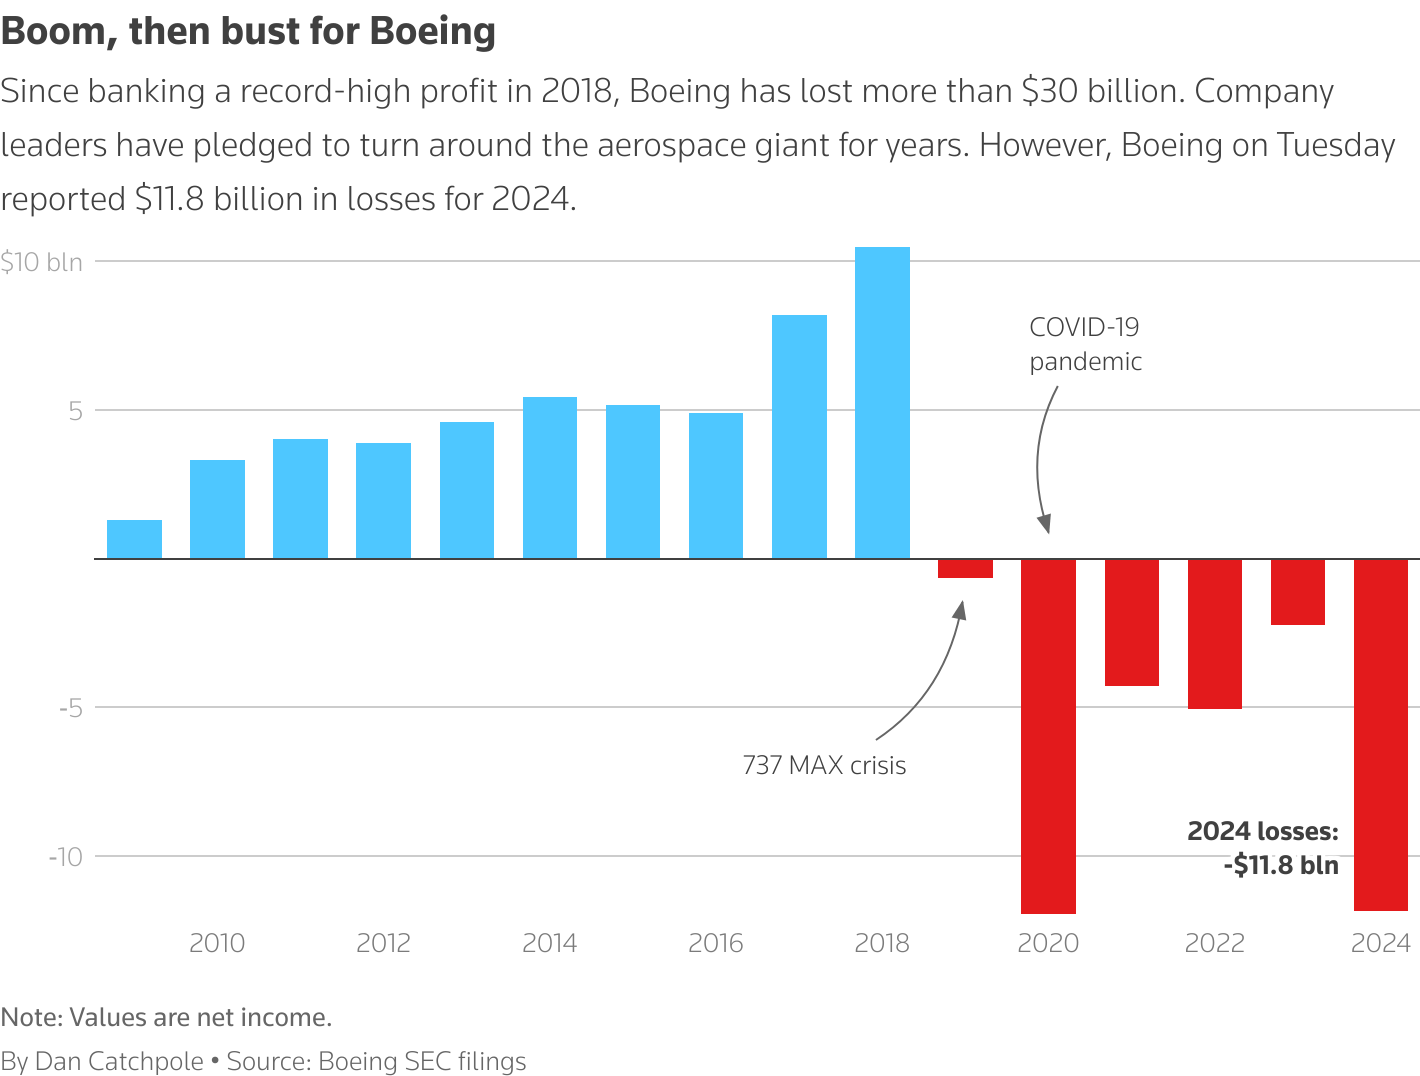
Here’s a more recent chart:

Ouch.

What had happened is that Boeing was forced by the Clinton administration to merge with its competitor McDonnell Douglas in 1997. McDonnell Douglas was an “MBA” firm. Boeing was an engineering firm. The takeover changed Boeing’s culture and leadership, engineering became secondary and for over 20 years, it was good to be a stockholder.

But Boeing’s ability to make and design planes took a huge hit, there were massive quality problems and employees below the executive rank were angry and demoralized. Boeing planes started falling out of the sky. They were unable to make reliable rockets any more and eventually spending all their time on juicing profits blew up in the face.

This is a general law. The same thing happened at General Electric. If you’re old enough you remember GE as an American industrial giant, making everything from turbines to washing machines. It was a technological pioneer. Then Jack Welch took over, started firing 10% of employees every year (the “lowest performers”, supposedly) and turned GE into a finance company. After all, profits from finance are much higher than profits from manufacturing.

Unfortunately, as with American car companies, GE wasn’t really a bank. Its financial profits were still dependent on being a major industrial company, but Welch didn’t believe in manufacturing. And now GE is a shadow of itself. Jack Welch? Well he got rich, he was lionized as one of the great CEOs of the era, and he retired before GE went completely to hell.

GE will never recover, and with it went a big chunk of America’s industrial and technological might.

And it’s unlikely Boeing will really recover. If it wasn’t for China, it would be possible. But China’s building its own civilian airliners now. They’re not caught up yet: they can’t make the jet engines, but they will be able to soon. (They make excellent jet fighters, probably better than the equivalent American planes, as performance in the recent India/Pakistan border incident showed.)

So China’s likely five years out from producing cheaper more reliable planes than Boeing, which is to say, cheaper and more reliable than American jets. The European market is going to turn hard away from Boeing due to Trump’s games and their having Airbus jets as an alternative. So what’s left for Boeing? Geopolitical risk is too high for anyone but Americans to buy their planes, and Chinese jets will cost less. If you don’t want Chinese, buy European.

They screwed up the rocket they were building for NASA, giving the market to SpaceX by default (and perhaps soon other new companies.) American fighter jets are worse than Chinese jets, and even if they’re better than some other alternatives, the market is crashing on them, because with modern software, you can’t use them if the US decides to stop you. They effectively have a kill switch. Given the US has recently threatened both Europe (Greenland) and Canada, who the Hell wants to buy an American jet, when America is the danger?

Buy Russian. Buy Chinese. Buy European. But American? You’d have to be a moron.

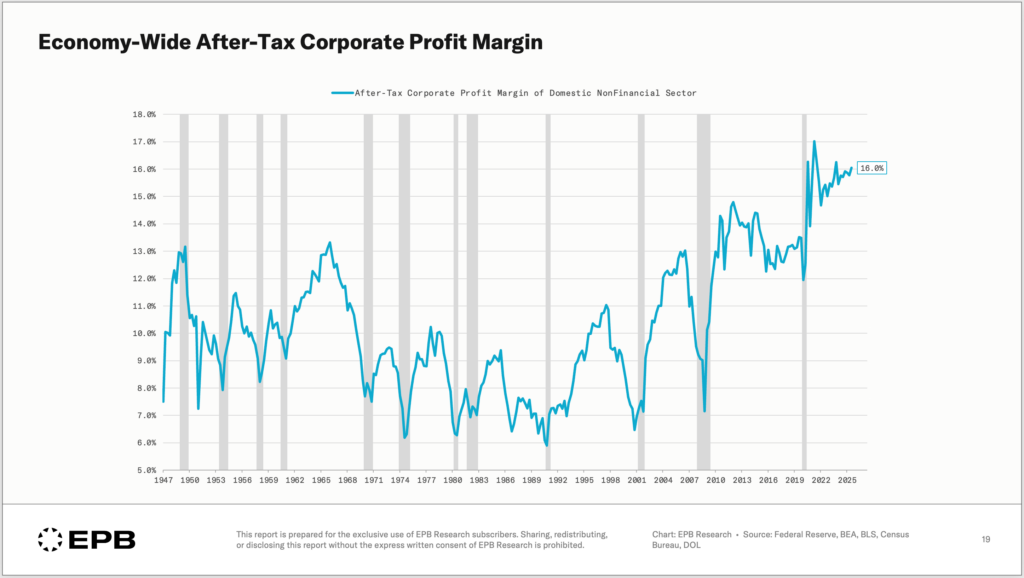
Now let’s look at the US economy overall:

The entire US economy is being burned down. Those high profits aren’t a sign of health, they are a sign that excess profits are being taken at the expense of reinvestment in production and tech; of too high cost structures that make producing in America too expensive (because those profits indicate higher prices); of non-competitive markets, and, generally speaking, of burning down companies or the economy, or both, to make unsustainable profits.

The problem is simple enough. China’s now ahead in 89% of techs. Prices for its goods are much lower. Who the Hell is going to buy American goods? Two years ago there was an answer. American allies would, even at higher costs, because they were scared of China and wanted to stay on America’s good side. But now? After America has proved more dangerous than China to Europe and Canada and after Trump’s on-again, off-again tariffs and other insane trade moves?

China’s looking mighty good, and America is the threat.

Oh people will still “invest” in the US, if you want to call it that. If America’s in its final stages of burning down the house to generate high profits, why not? But I suspect that even that is going to drop significantly because the geopolitical and exchange rate risk is just too high. As America declines, the US dollar will as well, and when you adjust for drops in the dollar, those returns aren’t going to look so great to non Americans.

The “Burning Down the House To Generate Heat” metaphor is one for our age. Not just for Boeing or America and its economy, but for humanity and ecosphere.

Welcome to the end of American Empire.

This site is only viable due to reader donations. If you value it and can, please subscribe or donate.


American and Chinese Elites Both Achieved Their Goals

Chinese and American flags

The period around 1980 was pivotal to the fate of nations. In the West Thatcher and Reagan came to power and finished the destruction of the post-world War II order, setting the West on a new path. This process had been ongoing since 1968, but the form of the new consensus was not clear until Reagan’s victory: financialization, crushing workers, destroying the middle class, asset bubbles and so on.

In 1978 Deng came to power in China and instituted reforms, especially market ones. This coincided with the West, and especially America, wanting to offshore and outsource their industry. This increased profits and impoverished the working and middle class. It financialized the economy: you could have the profits without the production and without dealing with uppity and powerful workers.

Reagan went after unions hard, Thatcher broke the miner’s union, the most powerful in Britain. The Federal Reserve started a long term policy of raising interest rates every time wages rose faster than inflation, meaning that over a period of decades wages rose less than inflation, and thus were reduced in real terms. The BLS moved towards understating inflation systematically, to undercut things like pensions with cost of live adjustments and to help “boil the frog”. Every change in how inflation was measured, for decades, which I am aware of, reduced the measured inflation rate. That doesn’t happen randomly or if your goal is the accurate measure of inflation.

Deng lucked into a geopolitical moment, and knew exactly how to take advantage of it. “Tired of dealing with uppity workers? Hate environmental regulations? Want more profits without the work of production? Move your production to China and we’ll make you rich!”

Deng exactly spotted the West’s weakness and knew how to take advantage of it. He also delivered: offshoring and outsourcing did make the West’s elites, and especially US and British elites filthy rich.

In exchange China got the industry and with the industry came the know-how and the technology. The technological lead always (always) moves to the country with the factory floor, and so it did in this case. It took quite a while for this to become obvious, so people could fool themselves, but the movement was inexorable. The same thing had happened when the industrial base moved from Britain to America (with tons of British financing). It took about 30 years for the tech lead to follow the industrial base. In this case it seems to have been about 20 years from China taking the industrial lead to tech supremacy, but the movement was the same.

American elites, wanting to be rich without real work and to destroy their internal enemies, those pesky workers who wanted a cut, got what they wanted. In exchange they destroyed their empire, because the real basis of the American empire was industry and technology.

The Chinese got what they wanted: China became the world’s leading industrial and technological power and a billion people were lifted out poverty.

The Gods often grant want we desire, if we’re willing to work for it. American elites got their wish. So did the Chinese.

Welcome to the Chinese century.

This site is only viable due to reader donations. If you value it and can, please subscribe or donate.

Just How High Can Silver Really Go?

~by Sean Paul Kelley

Everyone is talking about gold topping $5k an ounce. The yellow metal is captivating and big moves by it tend to suck all the oxygen out of the media space regarding other metals. In 2025 gold rose a whopping 64% against all comers, i.e the dollar, the S&P 500, oil, Bitcoin and on and on.

Gold’s meteoric rise last year is a fucking piker compared to what silver did. Silver was the best performing asset of 2025 rising an astonishing 147%. Yeah you read that right. 147% from January 1, 2025 to December 31, 2025. This raises some important questions, such as why did silver, after decades of disappointing performance, blow past every asset this planet has to offer and consequently how high can it go? Does silver have a ceiling?

So, questions asked, let’s now examine the known and/or knowable variables affecting silver prices at present.

First, what’s silver’s all time inflation adjusted high? This depends on who you ask and how you measure inflation. By our current CPI measurement silver’s all time, inflation adjusted high was roughly $150 an ounce. This was in February 1980 when the Hunt Brother’s tried to corner the silver market. Now, as most of you know, Ian and I both distrust current inflation measures, like the CPI, because it overweights consumer goods with stable or falling prices, using accounting legerdemain like hedonic pricing which equates increasing computer chip power and/or efficiency as disinflationary. At the same time the CPI underweights prices of goods that are rising, like food and other non-durables.

Seriously, I defy anyone to tell me food prices are stable or falling: you can’t do it. The CPI does this primarily to avoid COLA adjustments on entitlements, cheating retirees.

Other measures of inflation, indices, weighting using purchasing power parity or other yardsticks, delivers an all time silver high closer to $190. So, I’m going to channel King Solomon and split the baby in half and call the all time high at $170. But however you measure inflation it’s clear silver isn’t even close to its 1980 Hunt Brother’s high.

Second, price moves in gold and silver are not coupled and have not been for at least 150 years. They don’t correlate. Gold is considered a safe-haven against fiat currency hyper-inflation or economic collapse. Silver, on the other hand, is essential to modern electronic manufacturing. So gold had a nice run last year, but silver was number one by a very, very wide margin, outperforming gold, the way Shohei Ohtani outclasses everyone else on a baseball diamond. Even as silver and gold have been decoupled since the late 19th century evidence is mounting that last year’s silver move might have been the opening act of their long awaited re-coupling.

Perhaps a précis on how and why they decoupled and what a re-coupling would look like is in order.

The first question is to ask, “how long were gold and silver coupled?” Well, from ancient times—yes, fucking Greeks and Romans ancient times—until the 19th century silver and gold traded at a 15:1 ratio.

Don’t believe me?

Consider then how the 1792 US Coinage Act established a 15:1 ratio between the two in our newly constituted republic. That said, during the next century—the 19th—a handful of rare developments coalesced to break the two thousand year old linkage between the two royal metals, thereby widening the ratio nearly exponentially.

First, the gold standard for measuring currency values between nations was established. It soon became the, well, gold standard for all international trade.

Second, the conventional wisdom prophesied the end of America’s silver boom—never mind that the aggregate value of silver mined in Arizona and Nevada had a notional dollar value greater than the California, Yukon, Deadwood, Montana and Alaska gold rushes combined. Gold’s price during the 19th century, due in large part by its merciless acquisition by European banks, blew out the ratio, decoupling the two metals for a century and a half. The ratio between the newly decoupled metals had widened from 15:1 to 50:1 by the turn of the 20th century. By the turn of the 21st the gap was nearly 100:1, in large part due to US government manipulation of silver prices. The US government sheltered a rentiers market in silver bullion for decades. Wholesalers got silver at spot prices. They then charged retail buyers high premiums and pocketed the sizable difference. This cozy arrangement, due to silver’s recent price moves is breaking down, and fast. Good I say.

That said, I argue, based on a reasonable man’s assumption, that the spread, now roughly 50:1, will continue narrowing and sometime in the next few years complete a reversion to its 2,000 year historical mean. That puts a potential price of an ounce of silver at $320 an ounce and might even overshoot a little bit, as reversions are wont to do at times. Overcorrections are a real thing. Hitting the Hunt Brother’s high of $170 an ounce is just a mental milestone, nothing more. The silver bugs are getting their revenge and how.

Now, my assumption is based on a single premise, a reversion to the mean/norm. Not a bad premise to base an assumption on, but not enough for intellectual coherence and honesty. So, let’s explore another variable: silver’s supply versus demand forecast.

What is the global supply versus demand picture like? In short, extremely unbalanced. The numbers are staggering. Aggregate global demand per year is 1.3 billion ounces. Annual global mining supply maxes out at roughly 850 million ounces. Let’s be generous and toss in recycling raising global supply to 1 billion ounces of silver a year available for industrial purposes.

The maths paints a grim supply picture: a whopping 23% gap between supply and demand. Because silver is the single most important industrial metal—it is in every electronic we own— demand is not going down any time soon. A single tomahawk missile requires 500 ounces of .999 grade silver. Yes, 500 ounces. See where I’m headed with this demand equation?

Why is it in everything? It’s the goldilocks of metals. Silver might not be as conductive as some but it’s less resistant than most. It doesn’t overheat like some and burn through plastic coating, but its best left exposed and uninsulated. It’s place in the bell curve of the electrical performance of all metals is right before the big bulge grows. Most of the time we want things good and fast. In reality, however, we must choose between good or fast, but silver? Well, silver gives you good and fast together. Goldilocks!
One big variable exists concerning global silver supply that has no easy short or even medium term fix. It’s physically impossible for global mining companies to ramp up mining production enough to even begin closing a 23% gap between supply and demand in any time frame less than 2-3 years. And this assumes no economic growth leading to increased global demand. That is some wicked nasty inelastic demand for silver and it has zero supply side answers, except very high prices that lead to retail silver owners cashing out. Central banks would have to print precisely three metric shit-tons of fiat currency to induce silver bugs to sell. I know some of them—they make rabid dogs seem like puppies—and they are adamant: no selling until the ratio reverts to 15:1. Until they get their ring there will be no huggy or kissy.

Another fundamental we ought mention are draconian export controls on bullion instituted by the Chinese central government. Note: China is the world’s leading consumer of industrial silver. It also has an extremely long and complex history using silver as its monetary base. Much, much less so with gold. If you want a book recommendation on the subject just ask.

Then there is our southern neighbor, Mexico, our number one supplier of silver to this day, is considering retaliatory tariffs on silver for United States because of Trumpian fuckery. Much fuckery there and I applaud Mexico’s president for sticking to her guns.

Consider as well dollar weakness and potential QE. Both point directly towards higher silver prices. Add to all this a wildcard fundamental hiding in plain sight: the magic price point that compels the addition of physical silver to the portfolios of Central, Commercial and Investment Banks around the globe. It’s a simple equation: storage costs fall as prices rise. At $40 an ounce there is no reason to hold silver in a vault. At $170? We’re getting close. At $300? Bingo! You’re goddamned right there is a reason. Such a development would spike demand by an order of magnitude as it would reinforce the powerful upward trend already in place. This is the dynamic that could at long last force the reversion of the gold to silver ratio back towards 15:1. Gold’s present price of $5000 an ounce implies a target of $333 per ounce of silver. In my opinion, and this is not investment advice, this is where we are heading. Right now. It may take 18-24 months, but it’s going to happen.

These are just some of the fundamentals. I can’t cover them all. If you think I missed an important one, add it in the comments, please.

Let’s talk about some technicals followed by sentiment.

Late in 2025 silver achieved a triple top breakout. Triple top breakouts are very rare in any asset. But when they occur they are an extremely bullish signal, conveying that there is no predictable upper limit to the assets potential advance. This is silver today. Silver hit $50 in October, backed down to the low $40s, made another run in November to try and overcome $50 and didn’t make it. But then in late November and all of December during the Santa Claus Rally silver blew through $50 and ended the year at $72.05. Market observers I respect, all unsure but all equally intuitive, explained the triple top breakout as the result of a handful of factors coalescing in the short term, such as Chinese export control tightening, high retail demand, Mexico threatening tariffs on silver, and a short squeeze on the Comex. This confluence makes sense to me.

The underlying technicals that lead to triple top breakouts are usually either a short squeeze or a gamma squeeze. In late 2025 silver underwent a short squeeze. But in early 2026 led by a bank frenzy to cover what were in essence some very large naked shorts in the SLV and PSLV ETFs, coupled by a bizarre change in margin requirements—from a straight percentage to one based on the notional value of the contracts (I mean, WTF?)—backfired spectacularly, leading to the rarest of rare technical developments, one I’ve only seen once in my life as an investor—the mythical unicorn, the gamma squeeze.

In short, a gamma squeeze “is a rapid [asset] price surge from [futures] trading, where heavy retail (read: investment banks, spk) call buying forces market makers to buy shares to hedge risk, creating a feedback loop that pushes the price even higher.” A gamma squeeze can be viewed as one powerful force intent on creating and sustaining an upwardly positive feedback loop “[where the] cycle escalates because as the [asset] price rises, market makers must buy more [futures or the hard asset] to cover their increasing delta risk, driving prices up further and attracting more call buying, often in low-float, i.e. low-volume [assets].” Silver is now, for all intents and purposes, in a virtuous rising feedback loop, leading to higher prices which force more buying to cover expected demand thus leading to higher prices. When it comes to shorting a gamma squeeze FAFO. You will lose your ass.

These developments all serve to reinforce my call late last year that silver is not on a cyclical bull run. It is engaged in a secular bull stampede.

Cyclical trends last between 3-5 years, represent basic price discovery and a market composed of two healthy opposing forces: supply and demand. Cyclical bull or bear runs tend to predict the business cycle as well, serving as a leading economic indicator.

Secular trends, however, are a different animal altogether. Like Earl Campbell, that human rhinoceros, running over middle linebackers like they were children, a secular bull or bear is powerful, based on large scale structural economic rearrangements, demographic realignments, and/or crushing but ‘unforeseeable’ externalities—like the Arab Oil Embargo of the 1970s or losing wars like Vietnam, Iraq, and Afghanistan——that leave robust long-term consequences, like inflation, busted supply chains, broken armies, revanchist politicians, rising internal violence and other variables, in their wake. Secular bulls or bears last decades, some as long as 40 years.

Now a word on sentiment. Sentiment is a fickle bitch, much like the muse. Nothing can bankrupt an investor with more rapidity and totality than a sudden turn in sentiment. Two forces, ultimately rule investing: fear and greed. Beware the latter and respect the former, said my mentor at Morgan Stanley.

Right now silver is flying under the radar. Everyone is talking about gold. It’s gold, why the hell not? Gold makes people febrile. I’ve literally seen it with my own eyes. I’ve felt my forehead warm up and my fingers get a sudden subtle itch when I’ve held certain gold coins in my life. I had a Julius Caesar gold aureus in the palm of my hand once. Wow! So I get why silver remains the red headed step-child of the metals market. And the lack of commentary on silver reinforces my conviction of silver’s inevitable rise to $250-$300. As I used to say when I worked on Wall Street, “buy the rumor, sell the news.”

It worked every time. And right now silver is hardly a whisper much less a rumor.

So, realistically at what price would I begin selling my silver?

$275-$300 an ounce.

I’m patient.

And certain.
How To Drive Domestic Production and Reindustrialization

There’s a lot of confusion over this topic, so let’s break down some of the factors.

The principle is that you need someone to buy whatever it is you want to produce. That means it has to be priced reasonably, and that you either have to have foreign or domestic consumers.

It’s often noted that before the British conquest of India, India had more textile factories than Britain. Britain destroyed them. Why? Because they wanted them to buy textiles made in Britain. Before that, the most important government action to create industry in Britain is that they forbid the export of wool to the Low Countries. Why? Because Flemish weavers were way better than British ones. But it doesn’t matter how good your weavers are if they don’t have wool. So the Brits kept the wool at home and pretty soon they had a textile industry. When cotton and mechanized looms came along they wound up selling the world. After all, there wasn’t any competition from India!

Imperialism, trade policy and technological advances for the Industrial Revolution win.

So if you’re a country which wants domestic production you need customers. Demand. It can be domestic or international. Now in traditional industrialization you need foreign customers usually, because your country is poor before industrializing. Almost everyone did it this way except Russia. America was a partial exception, having strong domestic markets and legacy tech inherited from British North America, but only a partial one: they sold a lot to Britain and Europe in the early years.

You also need the technology, and you get a lot of that from overseas unless you were Britain. This is true of pretty much everyone, including the US (which got huge investments from Britain), Japan (Britain first time, US for reindustrialization after WWII), South Korea (US), Taiwan (US), and China (US). Germany might be considered a partial exception in the 19th century, their industrialization story is startling and impressive (See “Cities and Civilization” by Peter Hall.)

But let’s say you’ve already industrialized once, and then partially re-industrialized. You have the remnants of a skilled workforce and you have good universities and technical institutes and a literate workforce. (Pushing it here, half of Americans are essentially illiterate.)

You’ve also got a fairly rich population and decent domestic demand, in global terms. In other words, there’s domestic demand sufficient to support more production than you’re doing. (How do you know? Well, all those imports indicate demand, don’t they?)

The problem is that foreign production is cheaper and quite likely better. (Remember those Flemish weavers.)

Now the first way to do it takes its cue from the Brits and wool. If you produce a lot of resources suitable for production, why are you selling them in the raw state?

There’s a few stages of this. If you’ve got oil, say, you could refine it in country before sending it overseas. In Canada it used to be illegal to ship raw fish overseas, but after NAFTA it got sent to the US to be stuck in tins or smoked or whatever. You shouldn’t be sending raw logs. You should refine bauxite into aluminum yourself. Copper into wires. Etc…

This only works if the current producers can’t just buy from someone else, but there are certainly still cases where this is true. (We’re about to experience very severe copper shortages, silver is already in shortage, and China has been using its control over rare earths like this.)

Tariffs come in when you want to make domestic production cheaper than overseas. If you’re just starting in an industry, it’s going to be. You can use tariffs (the US strategy during the 19th cnetury), you can force your currency lower than its market value (this is what China did) or you can use subsidies. Tariffs are under international agreement, essentially illegal, but Trump has made that a dead letter, so they’re possible again.

Tariffs are only useful, however, if you’re actually going to be increasing production. They do nothing if you aren’t. (Trump, pay attention.)

Now let’s talk about demand. If you need more demand for goods you need to increase the amount of money people can spend on whatever it is. There’s a number of ways to do that.

First is tax policy: tax poor and middle class people less and rich people more. Give them money, taken from the rich. Poor and middle class people spend most of their money on goods and services. Rich people, given more money, drive up asset prices. Note that this means income taxes. Get rid of general VAT taxes, you don’t want to tax consumption or in anything you want more demand create an exemption. You can also remove taxes on whatever it is you want people to buy.

Change other types of taxes to discourage short term trading, buying in secondary markets and future markets and encourage people with more money than they need to invest in production. High capital gains taxes on short term investments, for example. Tax rich people’s income highly, and send that to poor people or use it directly for investment thru the government. Tax corporation highly so they are encouraged to retain earnings and invest them. Get rid of stock buybacks, just make them illegal, like they were for much of the 20th century.

Second are any policies which drive up wages for the bottom 80% of the population generally.

Third are subsidies. Subsidize the cost of buying or manufacturing whatever it is. Europe, China and the US have all used this with electric vehicles.

Fourth are general market policies: you need competitive markets with few barriers to entry. You must make oligopolies and monopolies illegal and easy to break up or you must tightly regulate prices in monopolies. In general you don’t want any business to have pricing power, because if you give regular people money and business just jack up prices, demand doesn’t increase.

Fifth is breaking supply side bottlenecks. After the oil crises central bankers spent a lot of time deliberately putting downward pressure on wages because wage increases led to using more oil, all marginal oil increases had to come from OPEC and that meant inflation. So instead they pumped up asset prices like houses and stocks. If there’s something needed for production, you need to find a way to get enough for reasonable prices. Copper, coal, oil, silicon, rate earths, uranium… whatever. This may mean domestic production, it may mean trade deals, though domestic is better if feasible.

Sixth is that you have to reduce cost structures. Real estate, rent, interest rates, medical prices, and so on.These are costs: they make production more expensive and they soak up demand from regular people. If landlords can increase prices freely then, again, they’ll just take up any extra money that regular people get which would otherwise go to buying all those new products.

Seventh is making currency levels dependent on trade and not on financial flows. You want your currency low if you’re importing more than exporting, and high if you’re exporting more than importing BUT if you export a lot of resources, you need to find a way to reduce currency rates below what they’d normally be if you want manufacturing to increase. Doing all this means taming financial markets and making the central bank do what is necessary, which it often doesn’t want to, since it’s usually run by ex-bankers and traders.

Eighth is managing trade deals. It’s a lot easier to get a big enough market if you make a deal with another county or countries. “You produce X and we won’t. We’ll produce Y and you won’t, thus X and Y both have much larger markets. And we freeze other countries out of our market for these goods.” General free trade is usually stupid, managed free trade like this is smart.

Ninth is making your banks lend to producers at reasonable rates rather than lending to people whose actions will drive up asset prices instead.

This is a high level overview. Each point could support it’s own article, heck, it’s own book and I haven’t even hit all the high points.

But the point is that there’s a lot involved. Real policy is when a government tries to do something from all angles, not just one. You don’t just put on subsidies and hope for the best. You don’t just slap on tariffs and think “surely someone will start producing”. You have to actually use as many levers as possible to make it possible to produce: demand, supply, credit, market structure, smashing barriers to entry, avoiding pricing power and so on.

That doesn’t mean it can’t be done, that’s means you have to make it your main priority, the way it was for China for decades or for Japan for decades or for South Korea for decades. It doesn’t happen by accident, or if you only half-ass it. In fact half-assing it is likely to produce no noticeable results at all.

If Western countries want to reindustrialize, they can. But only if they decide they’ll do whatever it takes. Decline is baked in, resurgence takes effort.


This site is only viable due to reader donations. If you value it and can, please subscribe or donate.


Canadian LapDog Breaks For Exit After Trump Declares Dog Is On The Menu

Canada has cut a trade deal with China. This is what I have been suggesting for ages, and it’s finally happening. (Not, of course, because Carney reads me, but because it’s the obvious play and of all Western leaders he’s been the most resistant to Trump’s threats and blackmail.) Canada cuts a deal:

Chinese leader Xi Jinping and Canadian PM Mark Carney have announced lower tariffs, signalling a reset in their countries’ relationship after a key meeting in Beijing.

China is expected to lower levies on Canadian canola oil from 85% to 15% by 1 March, while Ottawa has agreed to tax Chinese electric vehicles at the most-favoured-nation rate, 6.1%, Carney told reporters…

…

In the deal struck on Friday, Canada will allow only 49,000 Chinese electric vehicles into the Canadian market at the 6.1% tariff rate.

The cap is in response to Canadian automakers’ fears of an influx of affordable Chinese EVs.

As well as relief for canola producers, there will also be reduced tariffs on Canadian lobsters, crabs, and peas.

I would expect that if the Chinese are willing to manufacture in Canada we’ll give on other things. The limit on autos is to get China to manufacture here. US manufacturers of automobiles are no longer reliable and Stellantis has started to pull out of Canada, there are no major “Canadian” manufacturers, so US manufacturers they must be replaced. The 100% tariff on EVs was to please the US (Trump can’t be pleased), and to protect Canadian jobs. Since those jobs are now at risk and almost certain to be lost, well…

The BBC says this move is in reaction to Trump’s on and off again tariffs, but that’s only half true. I keep noticing this in much of the media, they talk about tariffs and not about the annexation threats and both are a factor. You can’t have your primary trade partner be a nation which wants to invade you or break you up with covert actions and color revolutions. Then, of course, there’s Trump’s comments that the US doesn’t need anything from Canada. OK then, if you don’t need it, guess we’ll have to sell it to someone else, and since that has to go two ways, guess we’ll phase out buying American cars and buy Chinese instead.

This will break the ice for many nations. As I have argued for ages, even before Trump came to office, everyone needs to cut a deal with China because it’s the rising power. It’s already the most powerful nation in the world in many ways, and it will be in all ways that matter in less than ten years. Perhaps five.

But it’s also that you can make a deal with the Chinese. They keep their deals unless you cross very clear red lines like supporting Taiwanese independence. Even before Trump the US did not keep its deals. As a Canadian I’m aware that America just ignored trade rulings against it in favor of Canada even twenty years ago. America is simply untrustworthy, they don’t really believe they have to obey even rules they themselves have agreed to. Trump is “ignore inconvenient rules on steroids” but pretending he hasn’t just ramped up an already existing American characteristic would be delusional.

It’s also worth noting that this is, in the words of commenter Carborundum, “seismic”. Canada has been extremely hostile to China ever since Justin Trudeau was elected, including arresting the Huawei heiress for America, slapping on those 100% tariffs and multiple other incidents. We did this in order to keep America happy, calculating that we needed America more than China. (I never agreed, but I was in the minority). Under Justin Trudeau we were America’s second most faithful lapdog (no one can ever beat the UK when it comes to lick-spittle toadying.)

So this is, if not a 180 degree turn at least a 100 degree turn. Carney said all the usual bullshit about human rights and Hong Kong, but they were pro-forma. They won’t get in the way of a deal, and I suspect that public scoldings and statements along those lines will become much less frequent. The issues will be given a nod when some journalist asks about them and little more.

Canada was the first of America’s lapdogs to make a break for the exit after Trump decided dog was on the menu. We’ll see who goes next. Because when Carney said that this was preparation for the new world order (down, conspiracy types) he was right: the old world order is all but dead, and everyone has to re-orient away from the setting sun of America towards the rising sun, China.

This site is only viable due to reader donations. If you value it and can, please subscribe or donate.

Page 6 of 100

Powered by WordPress & Theme by Anders Norén