The horizon is not so far as we can see, but as far as we can imagine

Category: Financial Crisis

Market Rallies On News of Trillion Dollar Giveaway

Image by TW Collins

Image by TW Collins

Is anyone really surprised the DOW is up almost 500 points, after Geithner promised to give private investors almost $1 trillion to gamble with?

The details of the giveaway are fascinating.  I sure wish that I could get financing like this to play the market:

Under one part of the plan focused on bad loans, the Treasury will provide up to 80 percent of initial capital alongside investment by private funds. The FDIC would then offer debt financing for up to six times the pooled amount.

Now, unless I’m messing up my math, that’s 24/1 leverage.  If older details hold, and the 80% is a non-recourse loan, meaning that it’s secured only by the value of securities bought, then it’s even sweeter.

PIMCO has announced it’s interested in participating, which means that the plan has succeeded in one sense—it has the buy-in of some very smart money.  That doesn’t mean that it’s necessarily good for taxpayers, or that it will be good in the long term for the economy, necessarily, but at least it isn’t being laughed out of Dodge.  On the other hand, would you refuse 24/1 to one financing?  Or even matching funds, as contained in part two of the plan?

I sure wouldn’t.  And PIMCO have been scavengers before.  They bet heavily in Fannie and Freddie bonds after it was clear Fannie and Freddie were insolvent, which was a bet that the government wouldn’t shear bondholders when it bailed out Freddie and Fannie.  Smart bet, but not a good return for taxpayers, who would have been better served by letting Freddie and Fannie’s debtholders lose money.

I am becoming increasingly convinced that my original call was the right one: that the various bailouts would lead to Japanification.  For 20 years now, since its own bubble burst, Japan has had an economy which slips in and out of recessions like clockwork and which never ever really got good again.  In Japan’s case, the lousy economy was in large part because they left a lot of debt debt on the books of private corporations.  In America’s case, the debt may be transfered to taxpayers, but the end result is likely to be the same, only compounded by attempts to create secondary bubbles so that the toxic waste regains enough value to claim a win.

Given that Geithner’s trillion dollar giveaway has been greated ecstatically by the financial sector, I expect we’ll see more money used in this fashion.  This plan appears to be good for about $2 trillion of lousy debt ($1 trillion from the matching 1/1 program, $1 trillion from the high leveraged portion).  Total current toxic waste on the banks books is probably about $4 trillion, which will still have to be dealt with.

That money will have to be paid off, eventually.  Doing so will cost the US  and the world a great deal of future growth, and individuals a great deal of future income and employment.  As things stand right now, I don’t think employment levels as measured by employment/population ratios will recover in the forseeable future—post recession “full” employment will just be lower than pre-recession “full” employment.  There are still some ways this could be made to work for everyone, and I’ll discuss those at a later date.
More Details On Geithner’s Plan

US Gold Coin

US Gold Coin

Bloomberg’s has more highlights of Obama’s plan for toxic assets that will be unveiled Monday by Treasury Secretary Geithner.  Newer details include:

  1. Geithner will ask Congress to give the Treasury and FDIC more powers: to guarantee more types of debt, limit payments to creditors,  and break executive compensation contracts.
  2. The Federal Reserves Term Asset Loan Facility program (TALF) will expand to riskier assets. Financing will be 1:1, and will apparently include private partners (in a way similar to the Treasury fund) who will make the investment decisions.  Profits and losses will be shared between the government and the private sector.

I still don’t like the FDIC funding plan, because the public component is up to 97%, but the Fed TALF plan makes a lot more sense.  Doing the funding 50% public, 50% private is much more fair, is not nearly as heavily leveraged (although leverage can be applied in other ways) and losses are shared much more equally, assuming these are not non-recourse loans (which they appear not to be, though that’s not certain.)

The additional powers Geithenr is asking for are acceptable, except for the ability to guarantee more types of debt.  The FDIC is already guaranteeing many bank assets: the idea of them guaranteeing even riskier classes only serves to set up  taxpayers to shoulder even more losses from the private sector’s.

Many of these concerns would be moot if the administration would just nationalize firms which are effectively insolvent. But, given that the administration won’t nationalize the banks, at least parts of this plan are not completely stupid.

The plan does however appear to perpetuate the trend of taking on private losses and putting taxpayers at risk for most of them.

Why Financial Crises Will Keep Happening

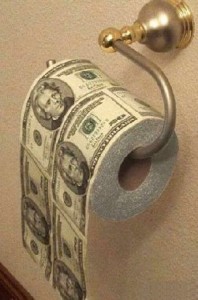
American dollar toilet paper roll

American dollar toilet paper roll

The financial crisis currently unfolding before our eyes in slow motion was inevitable and predictable. I say this because it was predicted by numbers of people. It was obvious; anyone with sense knew it was coming (a group which apparently includes very few people); and despite the fact that we’ve known for years it was going to happen, it happened anyway.

The same was true of the dot-com bubble. The inevitability of the dot-com collapse was obvious, at least as far back as 1996/1997. Everyone knew it who wasn’t paid not to know it, and it happened anyway and burst anyway.

Both of these foreseeable collapses raises the question of deliberate government policy—both bubbles were fostered and grown from tiny soap-suds with the aid of Alan Greenspan’s Fed and various other government and private and semi-private actors (in the case of the current collapse, including Fannie Mae and Freddie Mac).

Creating the bubble behind the current financial crisis took the cooperation and encouragement of a lot of people beyond the government, people who benefited a great deal from it. Let’s take Chuck Prince, the ex-CEO of Citigroup. Prince walked away from his near-destruction of Citigroup with about $41.5 million, including a $12 million bonus for his performance. The moral of the story is: drive the place into the ground, get paid well. Then there’s Merrill Lynch’s Stan O’Neal who walked away with $160 million.

Nice work if you can get it.

But if the rot was limited to the top, it wouldn’t be nearly as big a problem.

The Executive Coup

federal-reserve-seal

I’m going to discuss the administration’s plan to take toxic assets off the banks, then talk about what this and other moves this week (such as the FED announcing $1.15 trillion in new spending) tells us about the administrations plans for the financial sector and the economy, and how I believe they’re going to play out, as well as what the political power realities now are.

There are three parts to the plan to take toxic assets off the banks’ hands, of which we have mostly the details of the first part, in which the FDIC will form “private/public” partnerships to buy up assets.

  1. The plan has the FDIC loaning up to 85% of the cost of purchase as a non-recourse loan which is backed up only by the value of the loan.
  2. Of the remaining 15%, the treasury will lend up to 80%.
  3. The remaining 3% money must be put up by the private partners.

The government will share in any profits or losses of the underlying security, though we don’t know what percentage goes to the private investor or the public.

Think of the investment split in simple terms. If I want to invest in securities, why would I want a 3% partner with whom I have to split the return? If the government is investing 97% of the money, why are they even bothering with private partners? Why not just pony up another 3%? Oh sure, there may be some occasions on which the private partners put up more, but if the government thought they could get more, why are they offering 97% financing, with 85% being a complete write-off if the asset goes down rather than up?

There are two possible answers I can see.

Page 14 of 14

Powered by WordPress & Theme by Anders Norén